ServicesInsurance Claims
Insurance Claims Repair in Madera
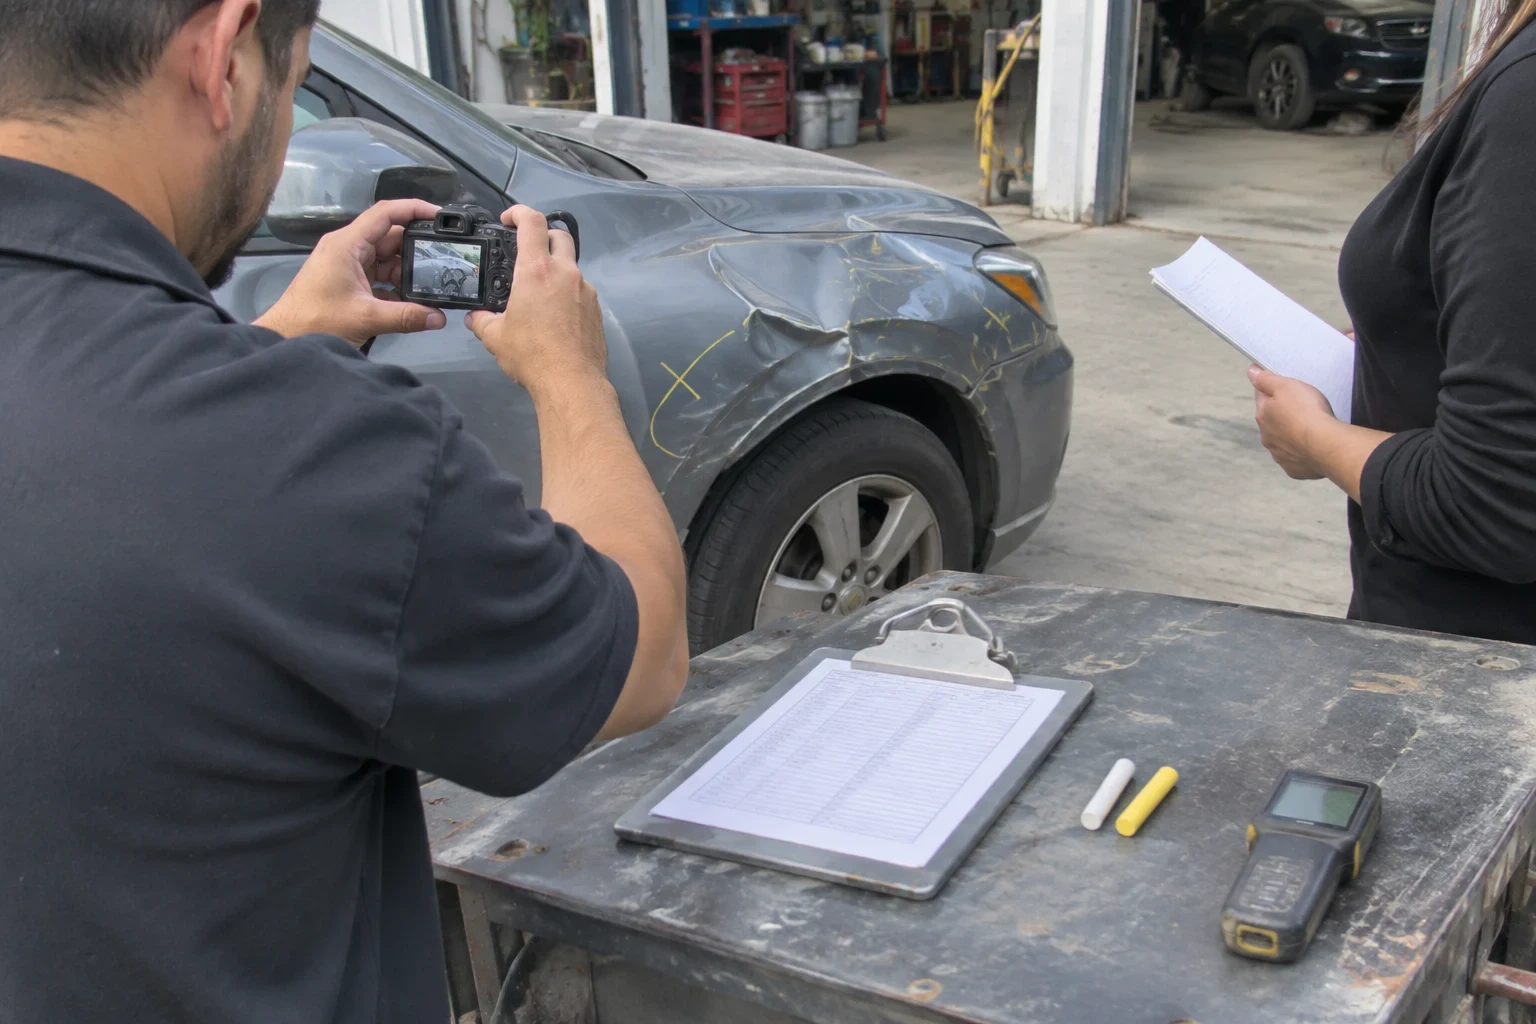
We work with your insurance company on the repair, not around it. We take the damaged area apart, find what the first estimate missed, send photos to the adjuster and fix your vehicle to the maker's repair steps so it is safe to drive again.
What we do on an insurance claim
After a crash, dealing with insurance can feel like a second accident. You end up with an adjuster's estimate, a claim number and a pile of questions. We take on the repair side of that. We write our own estimate, work out the repair with the adjuster and let you know where things stand.
Coverage decisions belong to your insurer and your adjuster, not to us. Our job is to show the insurer what your car really needs. A first estimate is usually written from the outside of the car. Bent brackets, cracked sensor mounts and crushed reinforcements only show up once the bumper and panels come off. We take photos of it and send a supplement so the repair includes it.
Our shop is I-CAR Gold certified, so our techs stay trained on current repair methods. On a claim, that counts most where your safety is on the line: the structure, airbags, seatbelts and the cameras and sensors behind your bumper.
What our claim help covers
- Our own written estimate
- We put together a line-item estimate for the repair. Lay it beside the insurer's and you can see exactly where the two don't match.
- Teardown and supplements
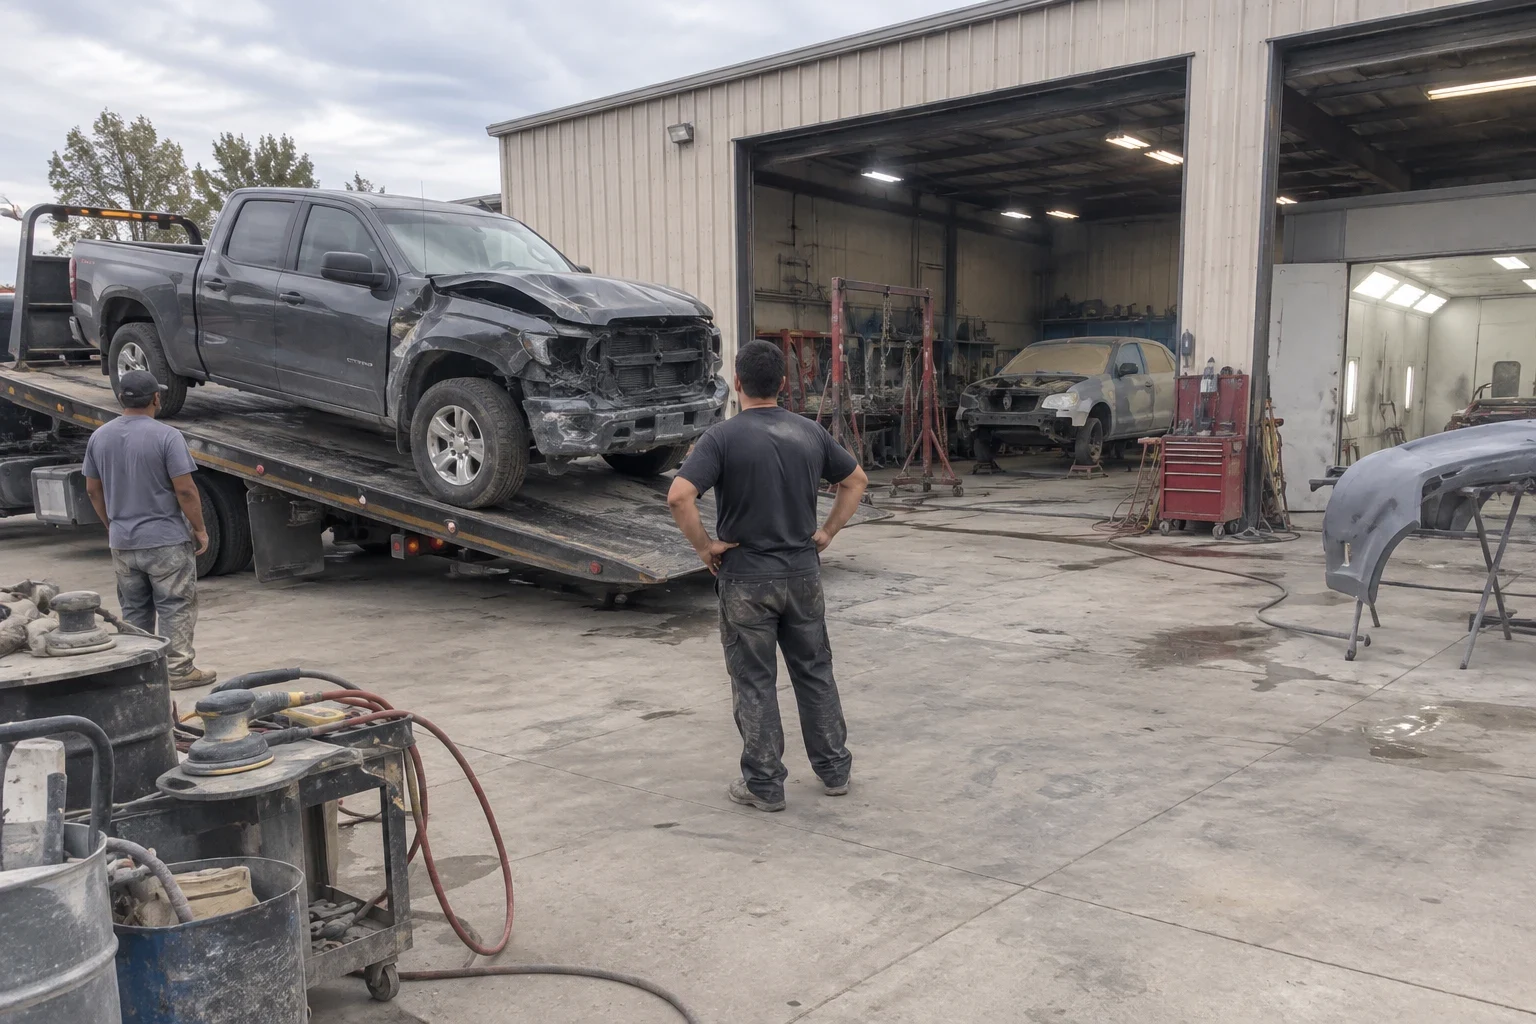
- Before any fixing starts, we take the damaged area apart. Anything hidden gets photographed and reported to your insurer. We wait for their okay before that part of the work begins.
- Repairs to the maker's procedures
- We pull up the automaker's repair steps for your vehicle. If they say a part must be replaced instead of repaired, or call for a certain type of weld, that's what we do, and we note the reason on the paperwork.
- Safety system checks
- After a hit we check airbag parts, seatbelt pretensioners and driver-assist sensors. Cameras and radar often need calibration once bumper or front-end work is done.
- Updates while it's in the shop
- You hear from us when a supplement is approved, when parts show up and when your car is ready. No need to keep calling for news.
- Final paperwork and photos
- We hand you a copy of the final repair bill along with our photos. Keep them for when you sell the car or if a question comes up later.
Signs your claim needs a closer look
The estimate was written from photos
A photo estimate only sees the outside. If the hit was hard enough to crack a bumper cover, there is often damage behind it.
Warning lights after the crash
Airbag, lane-keeping or parking sensor lights mean a safety system needs attention. That work belongs in the claim.
Doors or the hood don't line up
Uneven gaps or a door that sticks can point to structural damage. That may need frame straightening, which a quick estimate can miss.
The car pulls or the wheel sits crooked
A pull after a curb or corner hit can mean bent suspension parts. We check it before we sign off on the repair.
The insurer's number seems low
Low estimates often leave out calibration, paint blending or parts hidden behind panels. We compare it with ours line by line.
How a claim repair runs at our shop
- 1
Phone call and drop-off day
Have your claim number handy when you call, if you've got one. If you haven't filed yet, we'll tell you what your insurer is likely to ask. Then we pick a day for you to drop off your car.
- 2
Look-over and written estimate
We go over the damage, take photos and write up our estimate. If the adjuster wants to inspect the car or needs pictures, we deal with them directly.
- 3
Teardown and approval
We pull off the damaged parts and check what's behind them. Anything new goes to the insurer as a supplement. Extra damage doesn't get fixed until it's approved, so the bill holds no surprises.
- 4
Repair, calibrate and test
Structure gets fixed first, then body panels and paint. We calibrate the sensors, take the car for a test drive and make sure no warning lights are on.
- 5
Pickup
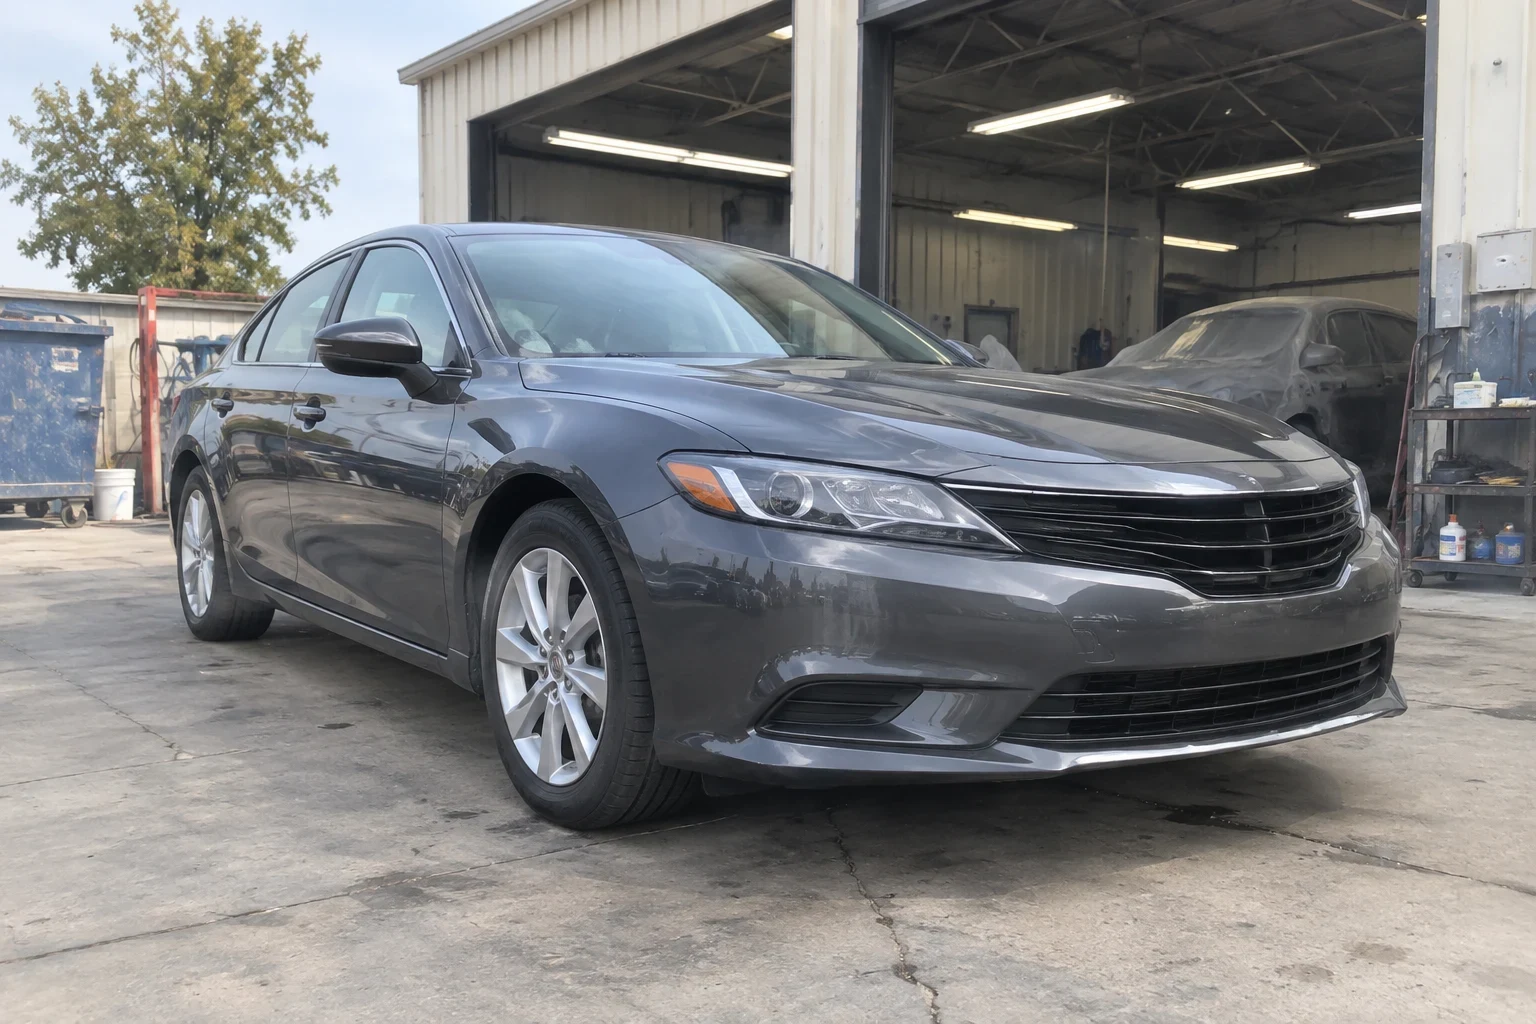
We show you what we did, go through the photos and review the final bill with you. If your claim has a deductible, you pay it when you pick up.
What affects your out-of-pocket cost
With most claims, your share is the deductible on your policy, and the insurer pays whatever is left on the repair it has approved. How big that total gets comes down to what is damaged and what a correct, safe fix takes. Deductibles and coverage are set by your insurer, not by us. What we can do is go over each line of the bill with you so nothing on it is a mystery.
- Hidden damage
- Whatever turns up after teardown goes into a supplement. That usually raises the insurer's share, not your deductible.
- Type of parts
- Some policies pay for new factory parts. Others allow aftermarket or used parts. We tell you what the insurer approved and flag any spot where the automaker's procedures call for factory parts.
- Sensors and calibration
- Many newer vehicles carry cameras and radar in the bumper, grille or mirrors. Getting those aimed right again after the repair takes time and adds cost.
- Paint blending
- To get the color to match, we often fade new paint out across the panels beside the damaged one. That way the side of your car looks like one color, but it takes extra labor.
- Your coverage
- Collision coverage, the at-fault driver's liability coverage and rental coverage don't work the same way. What gets paid is your adjuster's call.
Common questions about claim repairs
Something not covered here? (559) 546-7716
Can I pick a different shop than the one my insurer suggests?
Yes. California law lets you choose where your car gets fixed. Your insurer may point you to shops in its network, and if you're happy with one of them, that works. If you want us to do the repair, let your adjuster know and we'll coordinate with them.
What if the insurance estimate is lower than yours?
It's common. We back up each line with photos and the automaker's repair procedures and send those to the adjuster. Most gaps close once they see the proof. We won't drop a safety step just to meet a lower figure.
Can you work with the other driver's insurance?
Yes. When the other driver is at fault, you can open the claim with their insurer, and we deal with their adjuster just like we would yours. Your own collision coverage may apply too, and it can be quicker if the other company drags its feet.
Do you handle the whole claim for me?
We take care of the repair part: the estimate, the photos, the supplements and keeping you updated. Filing the claim and sorting out coverage, fault and rental cars stays between you and your insurer. If they ask you for something you don't understand, we'll explain it.
Will my car be as safe as it was before?
That's the goal on every job. We follow the automaker's repair steps, check the airbags and seatbelts and calibrate the driver-assist systems once the work is done. Then we take your car for a test drive before you get the keys back.
Get your claim repair started by phone
Give us your claim number if you have one and a quick rundown of the accident. We'll pick a drop-off day and tell you what happens after that. We work with drivers from Madera, Chowchilla, Madera Ranchos and the surrounding area.